Market Overview
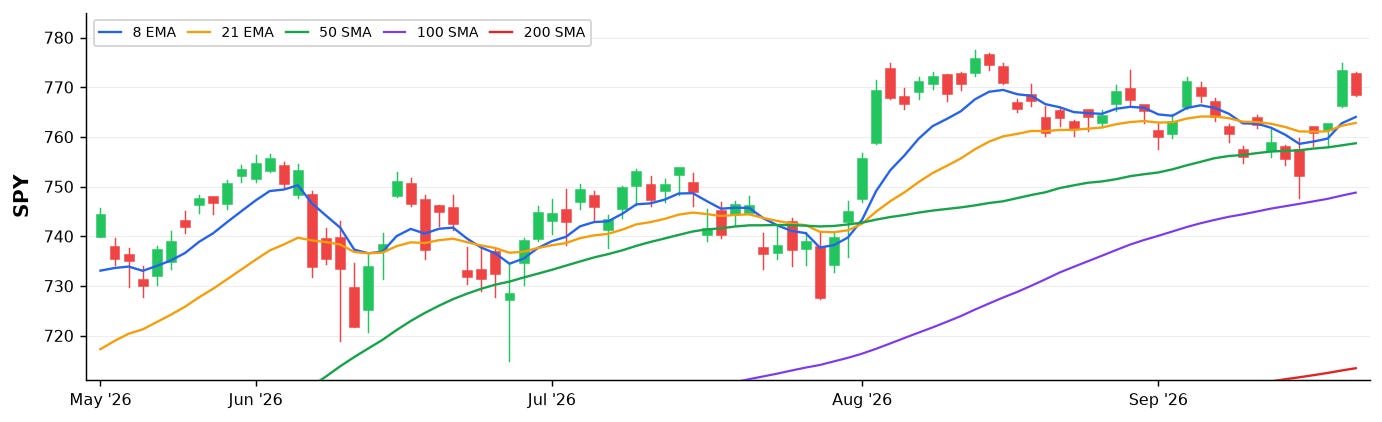
The SPY has now put together 3 consecutive closes above the 21 EMA and is trading around 768 today, well clear of both the 21 EMA at 762.80 and the 8 EMA at 763.99. The stack is intact and the 50 day at 758.72 is in the rearview. Monday’s surge to 773.50 was the real breakout move, and today is just digesting that gap higher. VIX sitting at 14.7 keeps the environment friendly. No reason to fight this trend right now.
Top Setups — 5 Signals
INTC — BULL · MEGA
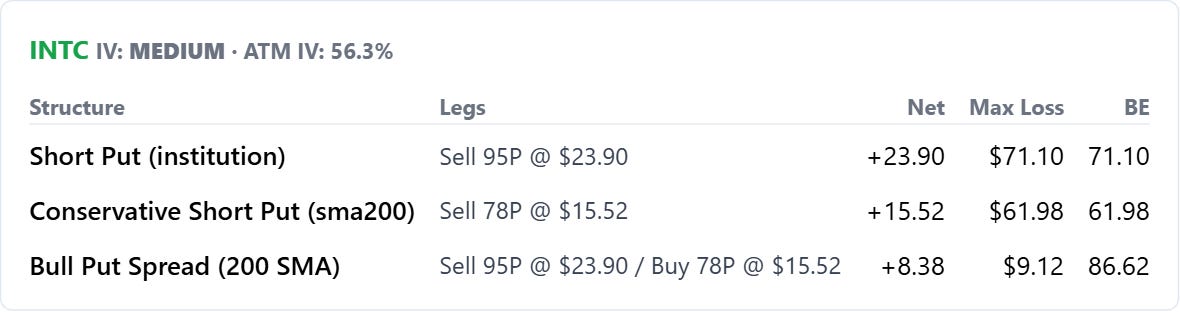
Puts Sold · Strike: 95.0 · Exp: Dec28 · 500 contracts · $1.2M
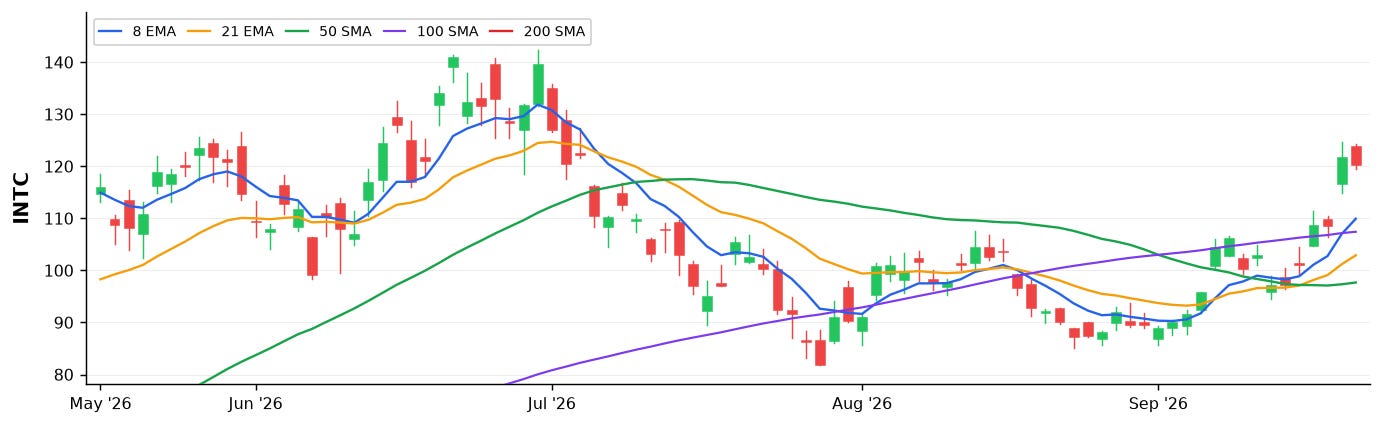
INTC is pushing 120 with the 8 EMA at 109.96 and the 21 EMA at 102.91 well below current price. Someone sold 500 December 95 puts for $1.2M notional, comfortable well below the 200 SMA and current price, which tells you they want defined downside exposure and are willing to own it much lower. XLK is outperforming SPY by nearly 6%, so the sector tailwind is real here.
PBR — BULL · LARGE
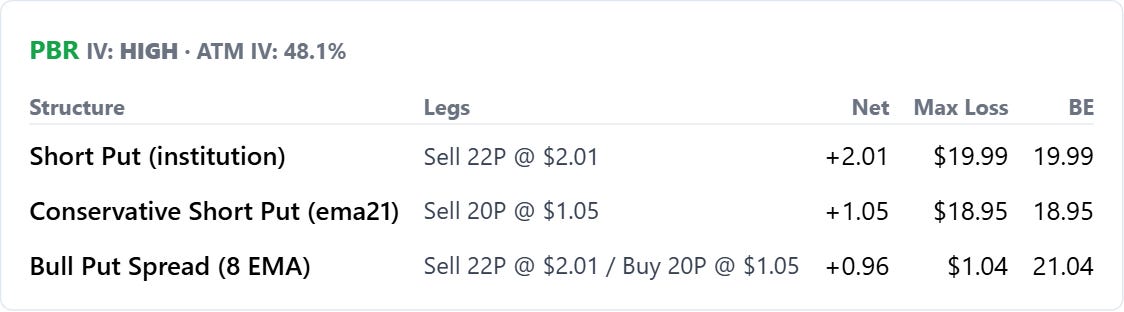
Puts Sold · Strike: 22.0 · Exp: Nov26 · 4500 contracts · $904K
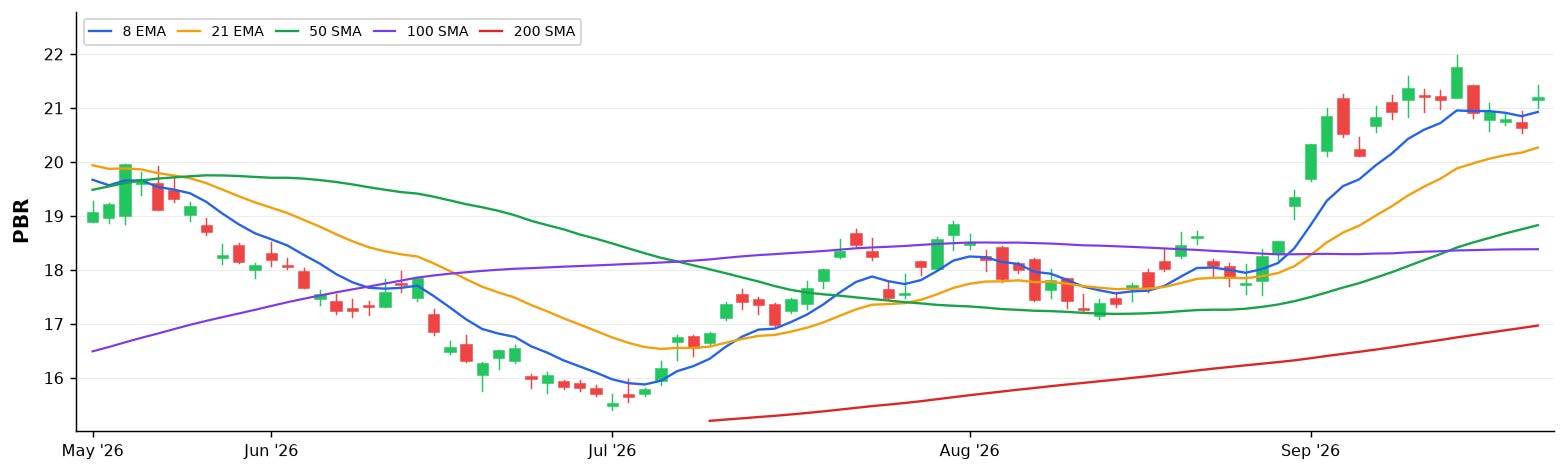
PBR is sitting just above the 21 EMA at 20.27 with the 8 EMA at 20.93, so the stock is in a tight EMA cluster and hovering right at an interesting inflection. The flow is notable: 4,500 November 22 puts sold for $904K notional, right at the money, which is an aggressive bullish bet that this thing holds and pushes higher. Weekly structure is clean with higher highs and higher lows above both the 50 and 200 week.
AMD — BULL · MEGA
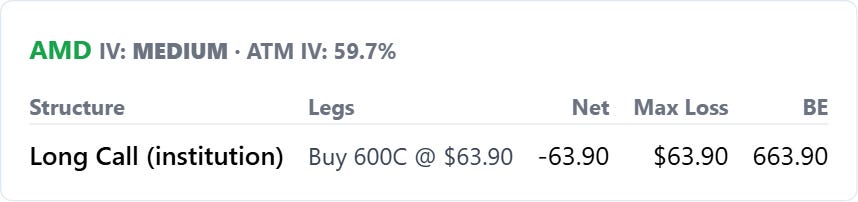
Calls Bought · Strike: 600.0 · Exp: Nov26 · 501 contracts · $3.2M
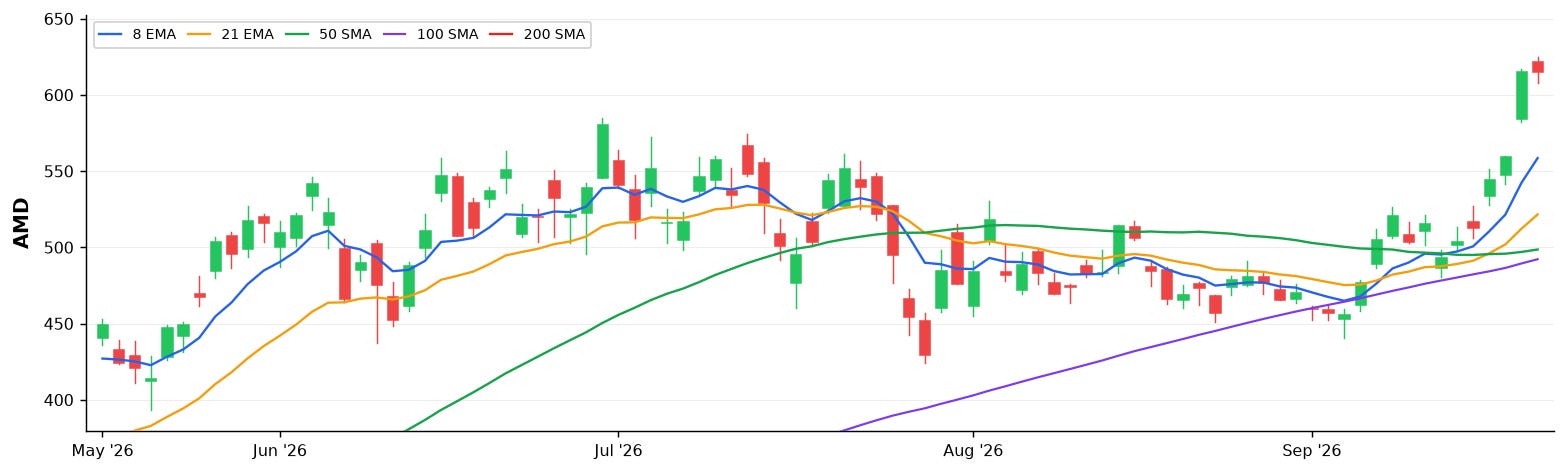
AMD is printing 612 with the 8 EMA at 557.99 and the 21 EMA at 521.37, both well behind it, and the stock is flagged as extended 2.4 standard deviations above the 8 EMA. Someone bought 501 November 600 calls for $3.2M notional, targeting a move through that strike, but given how stretched price is from the 8 EMA, chasing here is a tough risk/reward. Worth watching for a reset toward the 8 EMA before adding exposure.
TER — BULL · LARGE
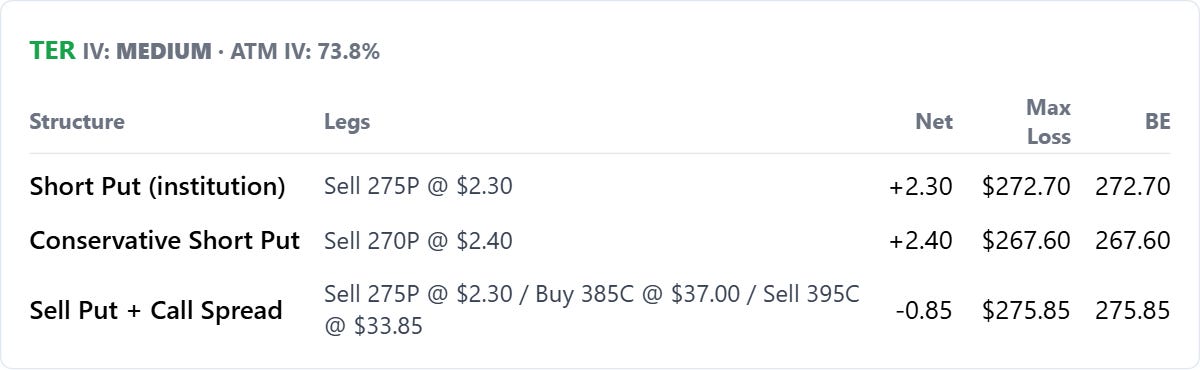
Puts Sold · Strike: 275.0 · Exp: Oct26 30th · 4600 contracts · $1.0M
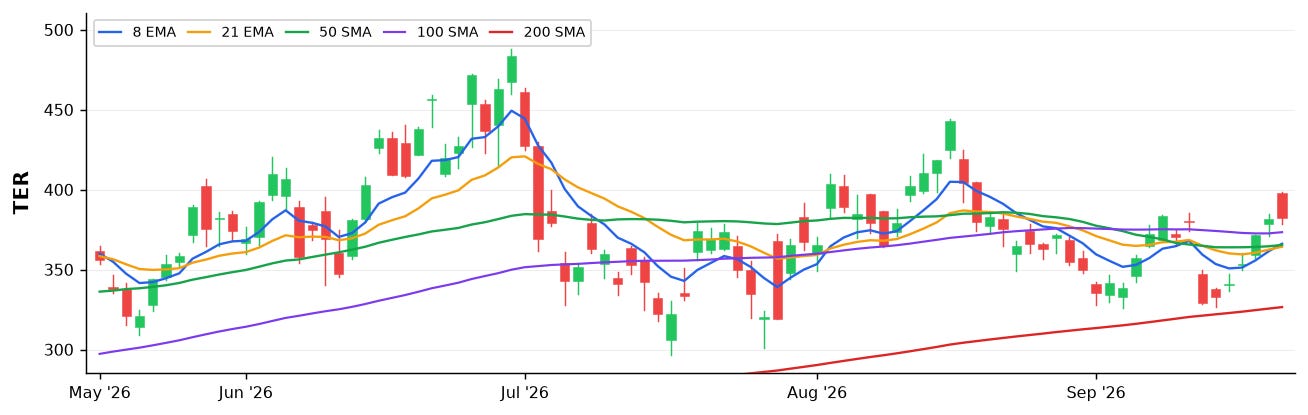
TER is trading 382.50 with the 8 EMA at 366.16 and the 21 EMA at 364.31 both sitting just below, giving you a logical support zone if the stock pulls in. The flow is a massive 4,600 October 275 puts sold for $1.0M, with that strike sitting a full 100+ points below current price, suggesting the seller is extremely comfortable with the current trend. Weekly structure is solid across the board and XLK as the sector backdrop helps.
NBIS — BULL · LARGE
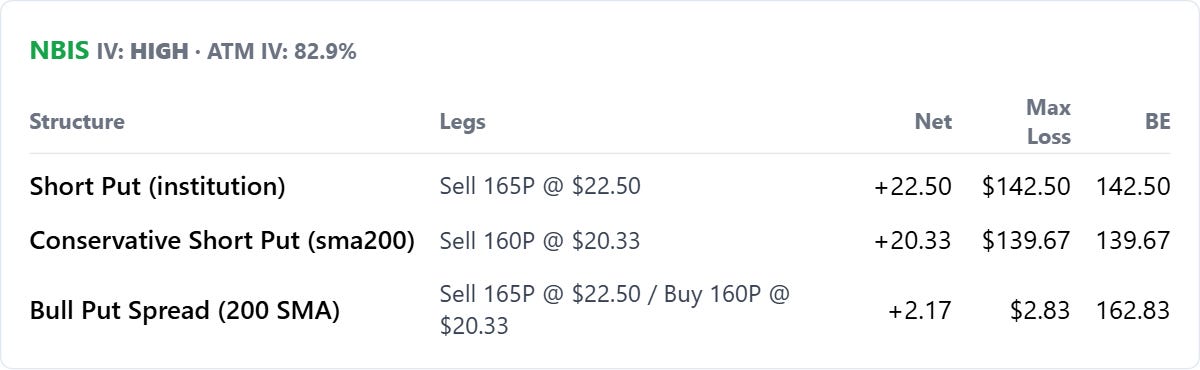
Puts Sold · Strike: 165.0 · Exp: Apr27 · 506 contracts · $1.1M
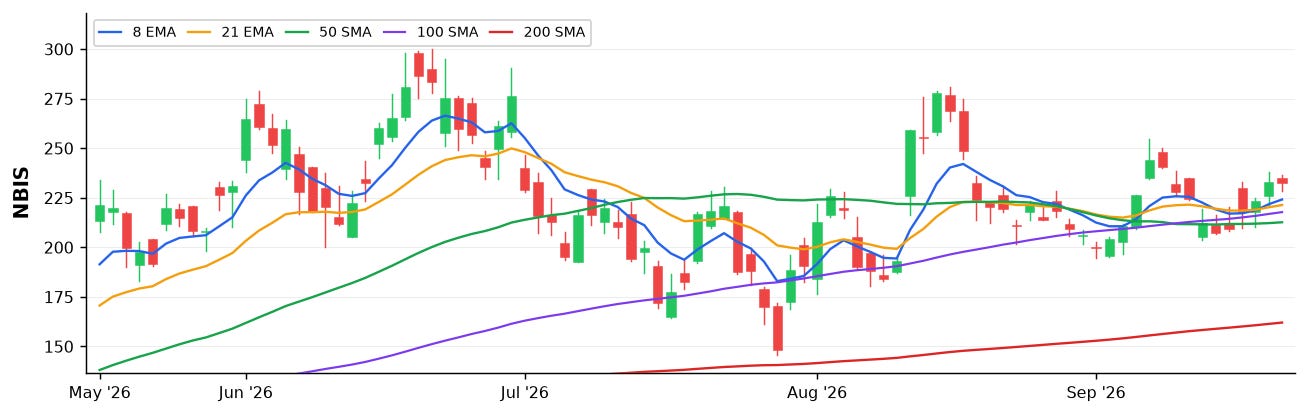
NBIS is holding 231 with the EMA stack aligned bullishly: 8 EMA at 223.88 and 21 EMA at 221.23 acting as nearby support. The trade is 506 April 2027 165 puts sold for $1.1M, giving the seller a long runway and a breakeven deep below current price. One flag worth keeping in mind is the sector: XLC is above the 50 but still under the 200, so this one runs more on its own momentum than sector strength.
Unusual Activity
🔔 JLL
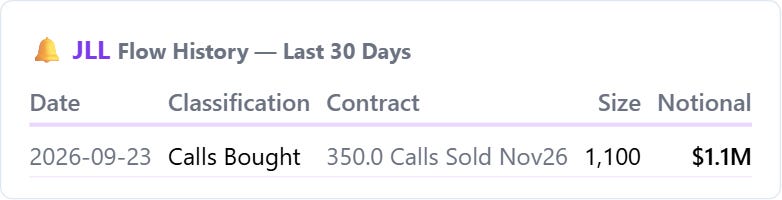
Calls Bought · Strike: 350.0 · Exp: Nov26 · 1100 contracts · $1.1M
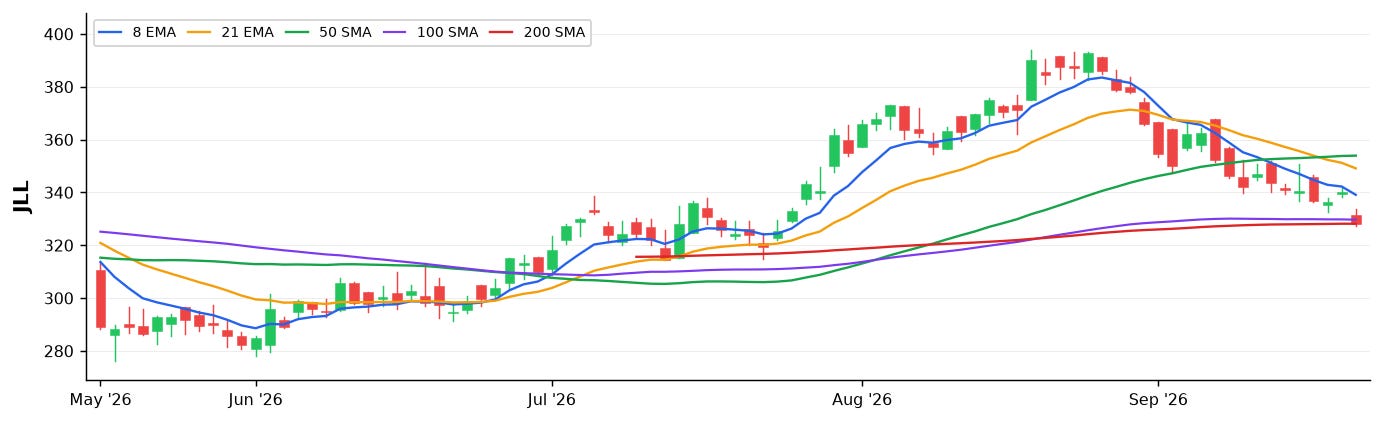
JLL saw 1,100 November 350 calls bought for $1.1M notional, a meaningful directional bet on a name that does not show up in options flow often. The chart is a bit tricky here: price at roughly 339 is sitting below both the 21 EMA at 349.13 and the 50 SMA at 353.94, so the stock needs to reclaim those levels to confirm the setup. The 200 SMA at 328.16 is holding as a floor, and the call buyer is clearly positioned for a recovery back above those overhead MAs.
Jones Lang LaSalle (JLL) is a Fortune 500 global commercial real estate services and investment management company operating across more than 80 countries. Its business spans leasing advisory, capital markets, workplace and project management, investment management, and technology solutions, making it one of the two dominant players in global CRE services alongside CBRE. The company has been on a strong operational run in 2026, posting record earnings-per-share in Q1, followed by Q2 revenue of $6.93 billion and adjusted EBITDA up 32% year-over-year, while completing a multi-year $1.82 billion share buyback program and launching a new $3.0 billion repurchase authorization.
Crime signal: LOW — The trade is well-explained by public information: strong consecutive earnings beats, a high-profile multi-year growth strategy unveiled at a March 2026 investor day, an expanded buyback authorization, a recovering CRE transaction market, and a Q3 earnings report falling within the November expiry window all constitute identifiable and publicly available reasons for a directional position at this size.
🔔 FTAI
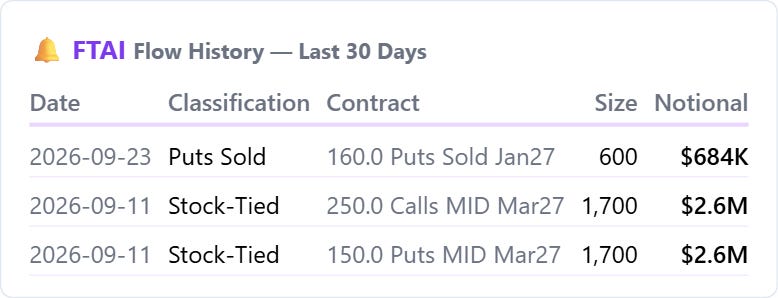
Puts Sold · Strike: 160.0 · Exp: Jan27 · 600 contracts · $684K
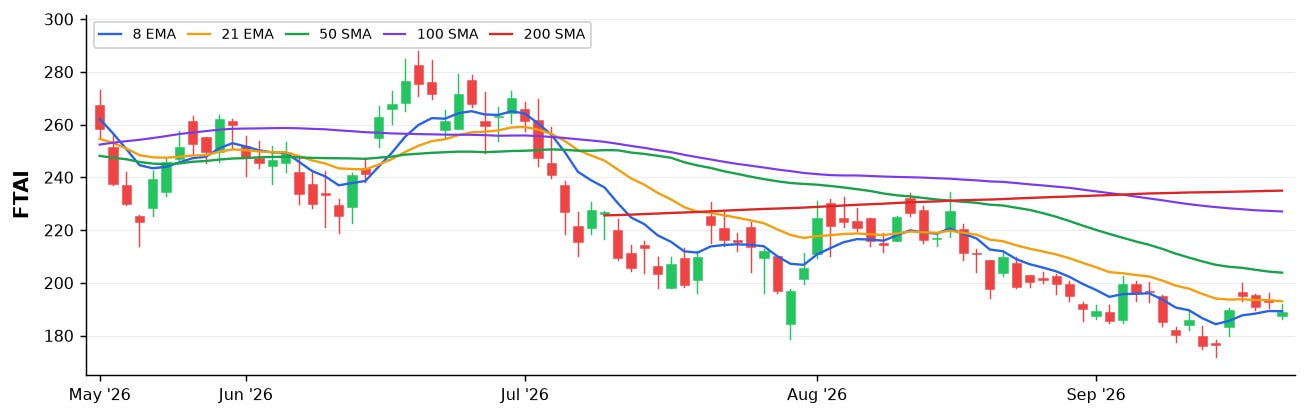
FTAI had 600 January 2027 160 puts sold for $684K, a bullish positioning trade with a long time horizon on a name that rarely sees this kind of options activity. The chart is under pressure: price near 189 is below both the 21 EMA at 193.04 and the 50 SMA at 203.87, and the 200 SMA at 234.96 is a long way overhead. The put seller is essentially saying the stock holds well above 160 through January, banking on stabilization even in a downtrend.
FTAI Aviation (NASDAQ: FTAI) is a New York-based aerospace aftermarket company that owns and manages narrow-body aircraft and engines through two core segments: Aviation Leasing and Aerospace Products, the latter focused on CFM56 and V2500 engine repair, refurbishment, and module sales. The company has been executing a deliberate shift toward an asset-light model, building out Strategic Capital Vehicles (SPVs) that deploy third-party capital into on-lease aircraft while keeping FTAI’s high-margin MRO and module businesses at the center. A third leg, FTAI Power, aims to repurpose commercial jet engines as aeroderivative power solutions for data centers, with a $1.465 billion anchor customer contract signed in Q2 2026. The stock has pulled back sharply from its 2025 highs near $235, is currently trading well below all major moving averages, and carries $3.4 billion in debt, making it a high-beta name with conviction on both sides.
Crime signal: LOW — The trade is directional but well explained by public information: a recently announced $500 million buyback, a $2.3 billion 2027 EBITDA guidance raise, and a near-term Q3 earnings catalyst that is broadly known, with the put sold well below current price providing a defined and rational risk buffer consistent with post-catalyst income generation rather than positioning ahead of non-public information.