

Market Overview
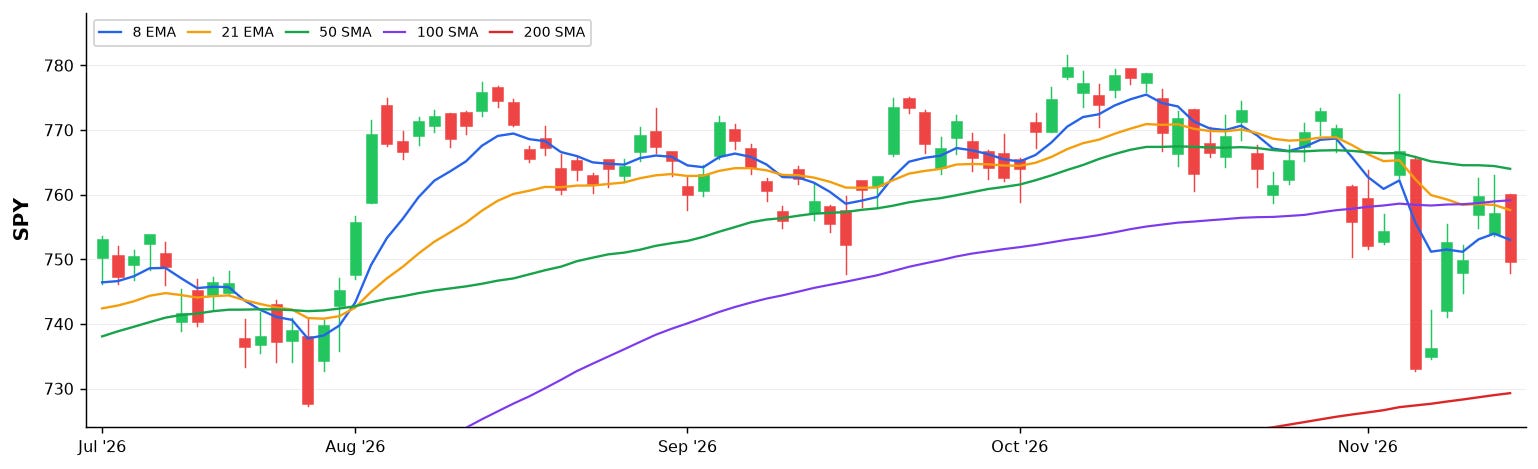
The SPY is going for its 3rd consecutive close below the 21 EMA today, and the action has been ugly. We saw a gap up to open at 760 but sellers showed up fast and pushed it down to 747.89 intraday before a slight recovery to 749.70. This is the third rejection of the 100 SMA. The 8 EMA at 753 and the 21 EMA at 757.62 are converging with a bearish spread, so overhead resistance is tightening. VIX at 20.4 is elevated enough to keep the pressure on bulls. Until we reclaim the 21 EMA on a closing basis, this tape has to be treated as a downtrend and not really a time to think about deploying new capital.
The dominant theme in morning flow is an aggressive AMD bull case, with over $23M in combined premium across call spreads, calls bought, and put selling across multiple strikes and expirations. SNDK is also seeing a cluster of call buying across the 800, 810, and 820 strikes for December, suggesting someone is positioning for a near-term move higher. On the bearish side, MSFT put buying and an ANET put buy stand out as the main counter-flow, though they are significantly smaller in notional than the bull side.
Before looking at the top set ups here is some interesting option flow, one of which I posted earlier on X (PCG).
PCG
There has been a lot of bullish flow in this name over the last month or so. Maybe something is brewing here? A few people in my Discord are long this name.

UNF
Two trades of interest in this name. Puts sold and then someone rolling out of the Jan27 270 calls into the Jan27 300 calls. I don’t typically show rolls as they are not deployment of new capital and depending on direction can be directionally bullish or bearish (but often trades that have gone wrong over time). The interesting thing about UNF is that the defining event for UNF right now is regulatory, not operational. Cintas announced in March 2026 that it would acquire UNF for $310.00 per share in a deal valued at roughly $5.5 billion. UNF is trading at a discount of roughly 25% to the deal price so this player is rolling a winning trade and hoping that the discount narrows. Risk is obviously that regulatory approval is not forthcoming. a spread this size is very wide by traditional merger arbitrage standards and reflects genuine deal-break risk. he primary risk to the thesis is FTC intervention. The uniform services industry is highly consolidated, and a combined Cintas-UniFirst entity would command an outsized share of the North American market. Regulators could demand material divestitures as a condition of approval, or could move to block the deal outright, either of which would cause the stock to reprice violently downward. If the deal breaks, UNF’s standalone fundamentals offer limited support at current levels: operating margins have compressed consistently throughout fiscal 2026, with the Q3 operating margin falling to 3.6% versus 7.9% in the prior year period, weighed down by over $20 million in transaction-related costs in a single quarter alongside ongoing ERP investment spending. A deal failure would strip out the acquisition premium, eliminate the cost discipline that deal pressure provides, and likely reset the stock to a range that reflects its deteriorating margin profile. If you are rolling a winning trade then fine but this is not a trade I would do taking a fresh position in this name. Risk Reward is potentially horrible - a total gamble.

